Guides
IRS tax checklist for US analytics contractors, from 1099s to quarterly taxes
Business analytics and intelligence contractors file Schedule C, pay quarterly estimated taxes, handle 1099-NEC forms, and claim deductions. Here is the checklist.
What to take away
- A US analytics contractor files Schedule C and Schedule SE with Form 1040, plus four estimated payments on Form 1040-ES.
- Clients report $600 or more on Form 1099-NEC, but you report the income either way.
- 2026 due datesApril 15, June 15, September 15, then January 15, 2027.
- Pay 90% of this year's tax or 100% of last year's to avoid a penalty.
- The 2026 business mileage rate is 70 cents per mile, unchanged from 2025.
Federal forms a US analytics contractor files
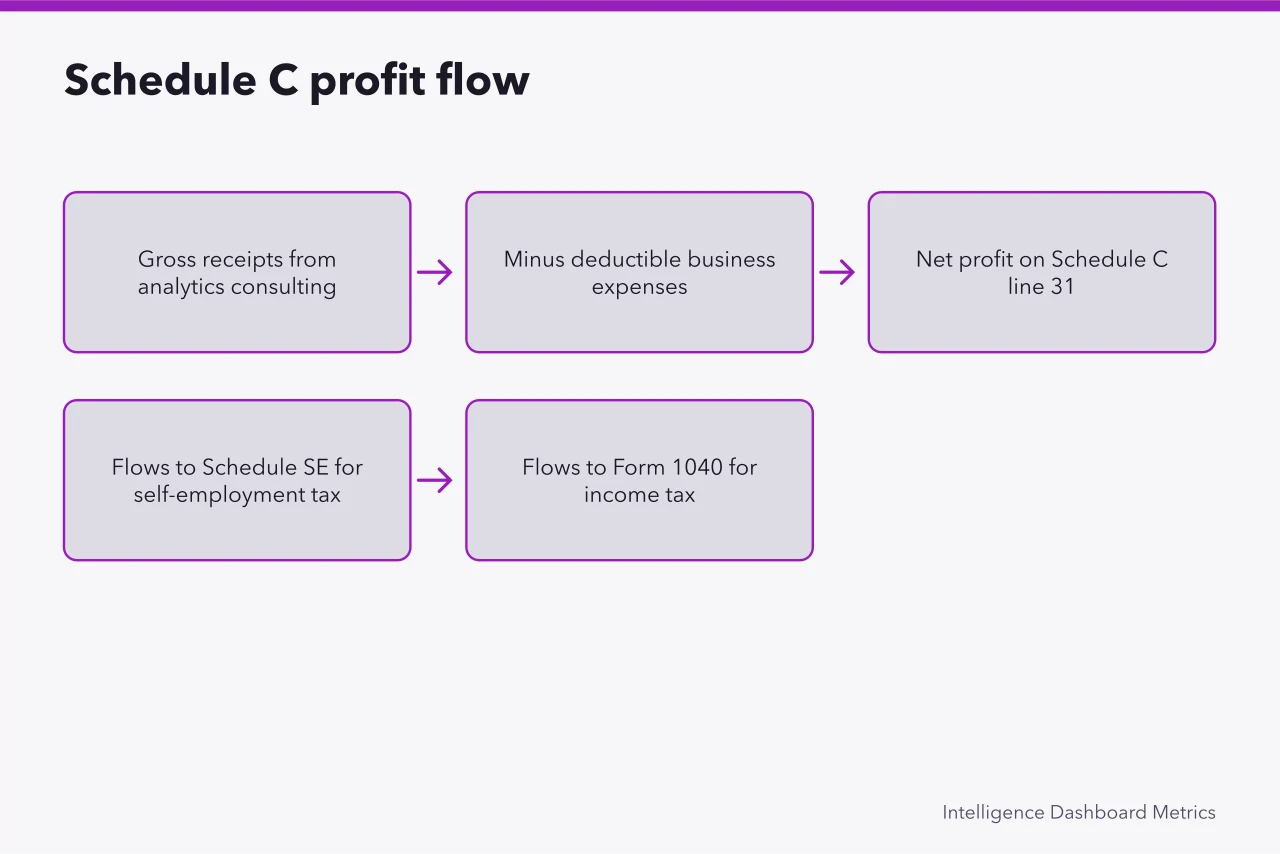
Three forms carry the federal filing. Schedule C reports gross receipts, expenses and net profit, and attaches to Form 1040. You file it whether or not a 1099-NEC arrived. A single-member LLC is a sole proprietor by default.
Most solo consultants use the cash method, counting income when received and expenses when paid. Line 31 net profit then flows to Schedule SE and Form 1040.
Keep business money separate, in a dedicated checking account, and report every payment, including amounts under $600.
Quarterly estimated payments and the 2026 due dates
No employer withholds for you, so you pay four times a year. Each payment covers income tax and self-employment tax together.
Quarterly estimated payments
| Payment | Due date | Income covered |
|---|---|---|
| First | April 15, 2026 | January to March |
| Second | June 15, 2026 | April to May |
| Third | September 15, 2026 | June to August |
| Fourth | January 15, 2027 | September to December |
A weekend or holiday moves a date forward. The IRS lists the rules and payment channels on its estimated taxes page.
Pay at least 90% of this year's tax or 100% of last year's to avoid a penalty. Above $150,000 of prior year adjusted gross income, the prior year figure rises to 110%. Quarterly estimated tax safe harbor rules works through the arithmetic for lumpy income.
Schedule AI of Form 2210 annualizes earnings when one quarter is heavy.
Handling 1099-NEC and 1099-MISC
A client paying $600 or more in a year sends Form 1099-NEC with the total in Box 1. The IRS page on Form 1099-NEC explains who must file.
Form 1099-MISC covers rent, prizes and legal settlements. Reconcile each form against your invoices in January and request a correction if a figure is wrong. Report the income anyway when a form never arrives.
Give each new client a W-9 with your legal name, address and taxpayer identification number.
Self-employment tax on consulting income
This tax funds your Social Security and Medicare. The 2026 rate is 15.3% on net earnings up to the Social Security wage base of $184,500, then 2.9% for Medicare above it.
Schedule SE multiplies net profit by 92.35% before applying those rates. Half of the result is deductible on Form 1040 as an adjustment to income, which lowers income tax and not self-employment tax.
W-2 wages share the same wage base, so a part-time job can cut your Schedule SE bill. The Additional Medicare Tax of 0.9% applies above $200,000 for single filers.
Deductions analytics consultants most often miss
Start with the items contractors skip.
- Health insurance premiums you pay for yourself or your family.
- SEP-IRA and solo 401(k) contributions.
- The business share of home internet and phone service.
- Tax preparation, bookkeeping and legal fees.
- Subcontractor payments reported on Form 1099-NEC.
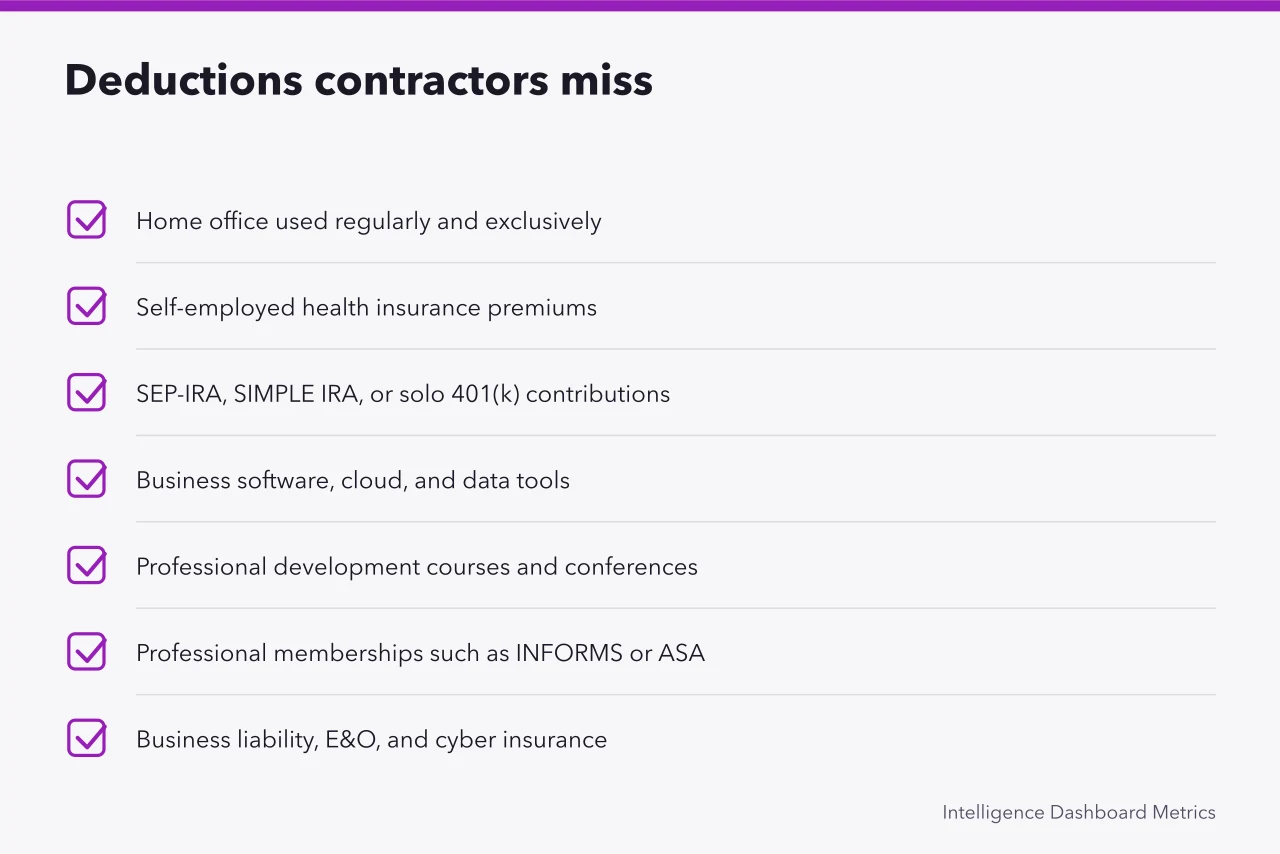
Health coverage is often the largest item, and Publication 535 explains eligibility.
A home office deduction requires exclusive use, not a separate room. Measure the space and compare its share of your home with the actual cost method. The simplified method pays $5 per square foot up to 300 square feet.
Retirement limits are indexed each year. A 2025 SEP-IRA allowed up to 25% of net earnings, capped at $70,000. A solo 401(k) allowed $70,000 in total, including a $23,500 deferral and a $7,500 catch-up.
For 2026 the announced figures are $72,000 and $24,500, still limited by the net profit on your return. A SEP-IRA can be funded up to the filing deadline, including an extension.
Equipment qualifies too. Publication 946 covers the Section 179 election and its vehicle rules. The 2025 limit was $1,250,000, phasing out above $3,130,000 in purchases, and SUVs over 6,000 pounds GVWR were capped at $31,300. A laptop and monitor for client work sit far below that ceiling. Software subscriptions are deductible when paid.
The 2026 standard mileage rate is 70 cents per mile, the same as 2025. Publication 463 compares that method with tracking fuel, insurance and repairs. Actual car expenses vs standard mileage shows when a low business-use vehicle does better with receipts.
Client meals are generally 50% deductible, so log the date, place and business purpose.
State tax and registration steps
Most states with an income tax use the same four dates as the IRS, but thresholds differ. California asks once you expect to owe $500, New York uses $300 and Virginia uses $150. Confirm the figure with your state revenue department.
Eight states levy no personal income tax on wages: Alaska, Florida, Nevada, South Dakota, Tennessee, Texas, Washington and Wyoming.
A single-member LLC registers with the state and renews each year. A sales tax permit matters only if you sell taxable goods.